
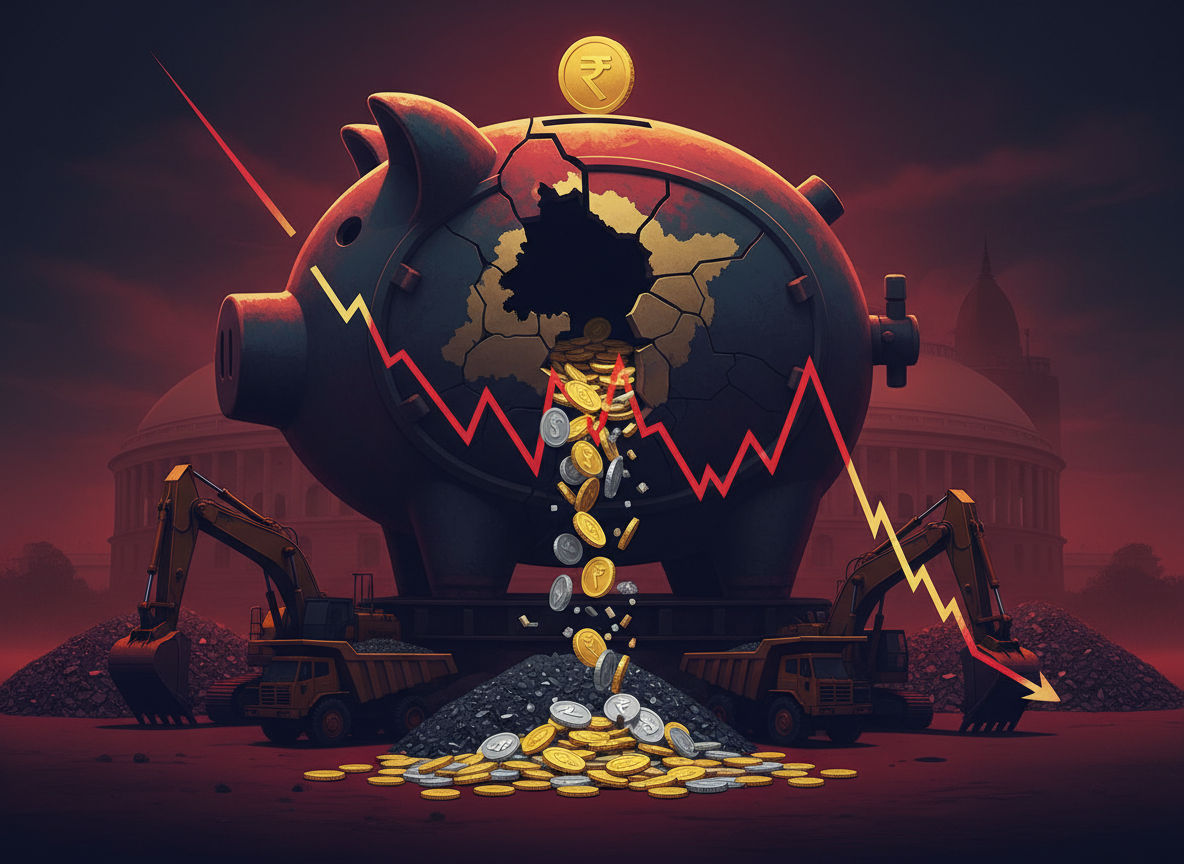
The fiscal implications is substantial for Odisha being the leading mineral producing states with the MMDR Amendment Act 2026. Based on mineral-production values for 2022–23 and 2023–24, and after deducting royalty and other applicable deductions, Odisha could have generated an estimated maximum annual revenue of approximately ₹3,550 crore under the 20 per cent ceiling prescribed by the ORISED Act. This represents not merely a one-time loss but a potential recurring annual revenue foregone by the state, both in the present and in the coming years.
Introduction
Opposition parties in Odisha are opposing the Mines and Minerals (Development and Regulation) Act 2026, arguing that BJP MPs in Odisha are silent on a crucial act affecting the fiscal autonomy of Odisha and causing a loss of around 12000 cr in annual tax collection. The main opposition parties, BJD and Congress, are in the same voice, protesting the Act and arguing it will cause mining revenue loss to Odisha. According to them, Odisha is going to lose the pending Rs 1,00,000 Cr and its future revenue and tax collection power is in looms with the central government taking control over the decision-making power on tax, revenue and share in mining and mineral products.
It is in the backdrop that the Mining and Mineral (Regulation and Development) Amendment Bill 2026 was brought by the BJP-led government in the Parliament of India and was passed without any critical discussion and scrutiny. This MMRD Amendment Bill 2026 added two major provisions to the original MMRD Bill 1957. First, ‘No tax, cess or other levy shall be imposed by the State Government on mineral rights; or mineral bearing lands, either based on mineral quantity or mineral value or royalty payable or otherwise’. Second, ‘invalidating pending tax, cess or royalty of various State Governments which is not yet deposited’. This will affect more than 20 states that get the share of revenue from mining and minerals resources.
Table 1. Addition of Two New Provisions in MMDR Act 2026

Mining and Mineral Value Production in Odisha
Odisha is the leading mineral-producing state contributing 45% of the total national value with ₹63,942 crore production value in 2023-24. Following are the states Rajasthan, Chhatisgarh, Karnataka and Jharkhand altogether contributing another 45% of the production value.
Figure 1 Top five state in terms of mineral value production in 2023-24

Source: Ministry of Mines, Government of India
Odisha has 120 operational mining in 2023-24. Its mineral reserves constitute 28% Iron ore, 24% coal, 59% Bauxite and 98% Chromite of India’s total deposits[1]. It has twelve industrially active zones/areas based on minerals namely. Rajgangpur, Ib valley area, Hirakud, Talcher-Angul, Choudwar area, Balasore, Chandikhol, Duburi, Paradeep, Khurda Tapang area, Joda Barbil and Rayagada area.
The revenue collection also has increased over a period of time from 670.51 Cr to 46,396.27 Cr in 2023-24. The last three-year (2021-24) average revenue was 44,776.81 cr. This way the total revenue collection in last two decades from 2004-05 to 2023-24 was Rs 2,18,272.22 cr.[2] Industry sector contributes 43.3% to the Gross State Value Added (GSVA) in 2023-24. However, within the industry sector, mining and quarrying contributes 22%[3] of the GSVA.
Figure 2. Mining Revenue Collection (in Cr) in Odisha from 2004 to 2024

Source: Directorate of Mines and Geology, Government of Odisha
A Fiscal Blow of Rs 3000 Cr Annually to Odisha State
The MMDR Amendment Act, 2026 represents a significant setback to the fiscal autonomy of mineral-rich states in India. Among the states likely to be most affected is Odisha, the country’s leading mineral-producing state by value. The amendment effectively targets the fiscal provisions of the Odisha Rural Infrastructure and Socio-Economic Development (ORISED) Act, 2004, whose validity was upheld by the Supreme Court of India in 2024. The ORISED Act provided for a tax on mineral-bearing land at a rate not exceeding 20 per cent of the annual value of such land[4].
However, the MMDR Amendment Act, 2026 introduces a categorical prohibition stating that “no tax, cess or other levy shall be imposed by the State Government on mineral rights or mineral-bearing lands, either based on mineral quantity or mineral value or royalty payable or otherwise.” This provision effectively eliminates the possibility of states imposing such a levy on mineral-bearing land in the future.
For Odisha, the fiscal implications could be substantial. Based on mineral-production values for 2022–23 and 2023–24, and after deducting royalty and other applicable deductions, Odisha could have generated an estimated maximum annual revenue of approximately ₹3,550 crore under the 20 per cent ceiling prescribed by the ORISED Act. This represents not merely a one-time loss but a potential recurring annual revenue foregone by the state, both in the present and in the coming years.
The amendment has an additional retrospective fiscal consequence. Another provision seeks to invalidate pending claims relating to tax, cess or other levies imposed by state governments but not yet deposited. This effectively closes the possibility of recovering such dues retrospectively from 2005 onwards—a recovery that had been permitted by the Supreme Court in its 2024 judgment. Thus, the amendment not only curtails the future revenue-raising authority of mineral-rich states but also extinguishes a significant potential source of past revenue recovery.
[1] Directorate of Mines and Geology, Government of Odisha
[2] Directorate of Mines and Geology, Government of Odisha
[3] OES Chapter_1(Main Booklet)_0.pdf
[4] act_1266285399_1436507613.pdf
About The Author


Leave a Reply